CLARKSONS HELLAS – SnP WEEKLY
This week, tanker activity has increased compared with the previous few weeks across most segments. VLCC spot rates appear to have established a near-term floor of around $500,000/day, with the global average across the…
This week, tanker activity has increased compared with the previous few weeks across most segments.
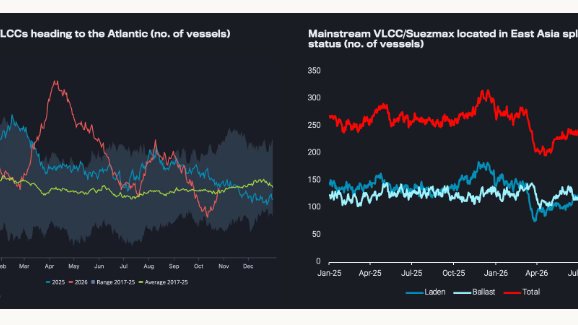
VLCC spot rates appear to have established a near-term floor of around $500,000/day, with the global average across the mainstream roots currently assessed at $564,300 today. In the product tanker market, contrary to much of this year, MR TCE averages are now at similar levels across both Atlantic and Pacific basins, with earnings captured globally being assessed at $86,500/day. Buying appetite continues to hold at firm, stable levels across all tanker segments as we observe a stabilization of the asset prices as well.
Meanwhile, according to Associated Press, US officials have cautioned regional allies about the possibility of renewed military strikes lasting several days following the 3 November elections, alongside potential Iranian retaliation against energy infrastructure.
Such developments could result in sustained damage to energy infrastructure or disruptions to shuttling operations, potentially reducing cargo availability for onward VLCC voyages and a reduction in cargo volumes could ultimately offset the positive impact of tighter vessel availability. Conversely, a decisive military outcome or a peace agreement enabling the resumption of safe, direct voyages could bring additional tonnage back into the market and put downward pressure on freight rates.
This story was originally published by Hellenic Shipping News. Read the full story at Hellenic Shipping News →
Conversation