Investors Are Piling Into Dangote. But Is the Price Right?
Nigerian downstream giant Dangote Petroleum Refinery has closed its public offer (IPO). It is now bringing Africa’s industrial ambitions onto investors’ balance sheets. The outcome is already substantial. However, questions remain about the investment…
Cyril Widdershoven is a senior maritime, energy, and geopolitical analyst and Senior Advisor at Blue Water Strategy, specialising in the strategic intersection of shipping, ports,…
Nigerian downstream giant Dangote Petroleum Refinery has closed its public offer (IPO). It is now bringing Africa’s industrial ambitions onto investors’ balance sheets. The outcome is already substantial. However, questions remain about the investment case. Yes, a refinery can transform a country’s energy security. However, it can still deliver disappointing returns to shareholders, especially if they pay too much for earnings that prove temporary.
After the October 27 celebrations, this distinction matters. Applications are still being checked, with regulatory approval of allotments and the start of trading ahead. Reports claim demand is roughly three times the targeted offer. Enthusiasm is clearly there, but final allocations and proceeds remain to be confirmed. The oversubscription shows appetite, especially at the offer price. However, it will not establish what the business is worth through a refining downturn.
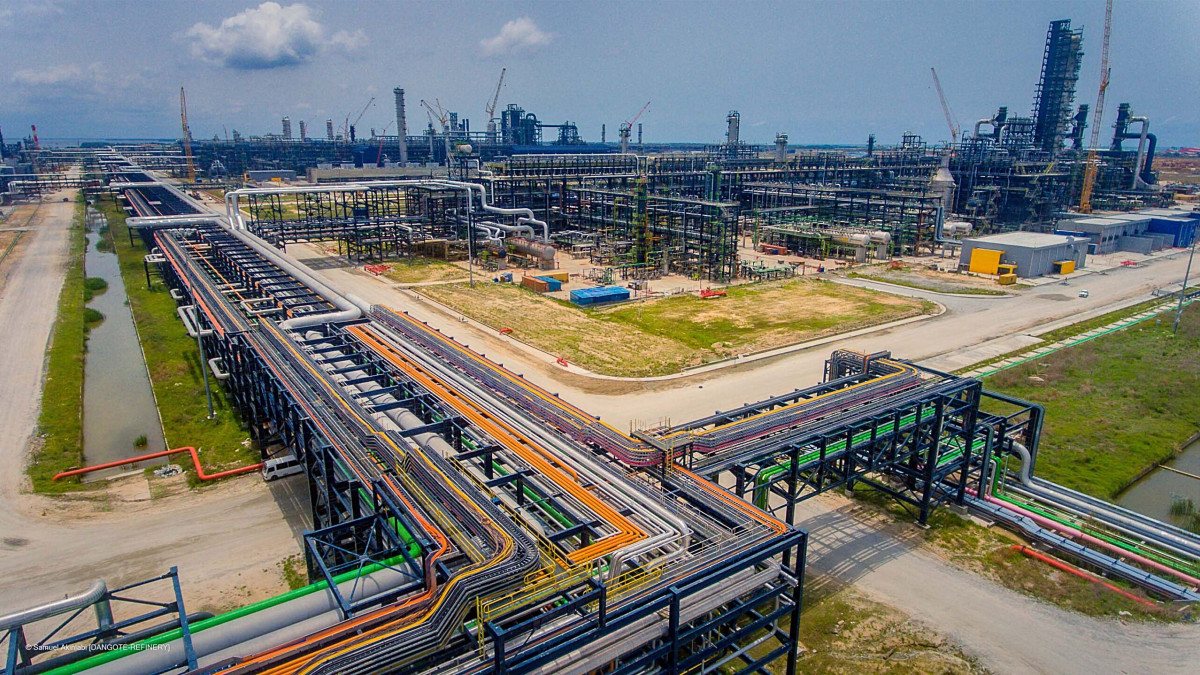
Still, a strong business lies beneath the publicity. Dangote’s coastal complex entails refining, petrochemicals, storage, and marine infrastructure, with current crude-processing capacity stated at 700,000 bpd. This scale will create opportunities to spread costs, compete with imported fuels, and supply overseas customers. For Nigeria, after decades in a corner, the overall strategic value is clear. From a shareholder's point of view, the challenge remains converting those advantages into durable cash returns.
This story was originally published by OilPrice.com. Read the full story at OilPrice.com →
Conversation