
Logistics Alert: Capacity SHRINKS for 11 Straight Months
The latest ISM Manufacturing PMI and LMI reports confirm what many in logistics already feel: demand is strong, but capacity is heavily constrained. Learn why transportation capacity is in contraction for the 11th straight…
The latest ISM Manufacturing PMI and LMI reports confirm what many in logistics already feel: demand is strong, but capacity is heavily constrained. Learn why transportation capacity is in contraction for the 11th straight month, pushing freight rates and diesel prices significantly higher. We break down the key numbers from October’s economic data, including surging production and new orders, coupled with historically low inventories. Prepare for continued high costs and tight networks as 2024 approaches.
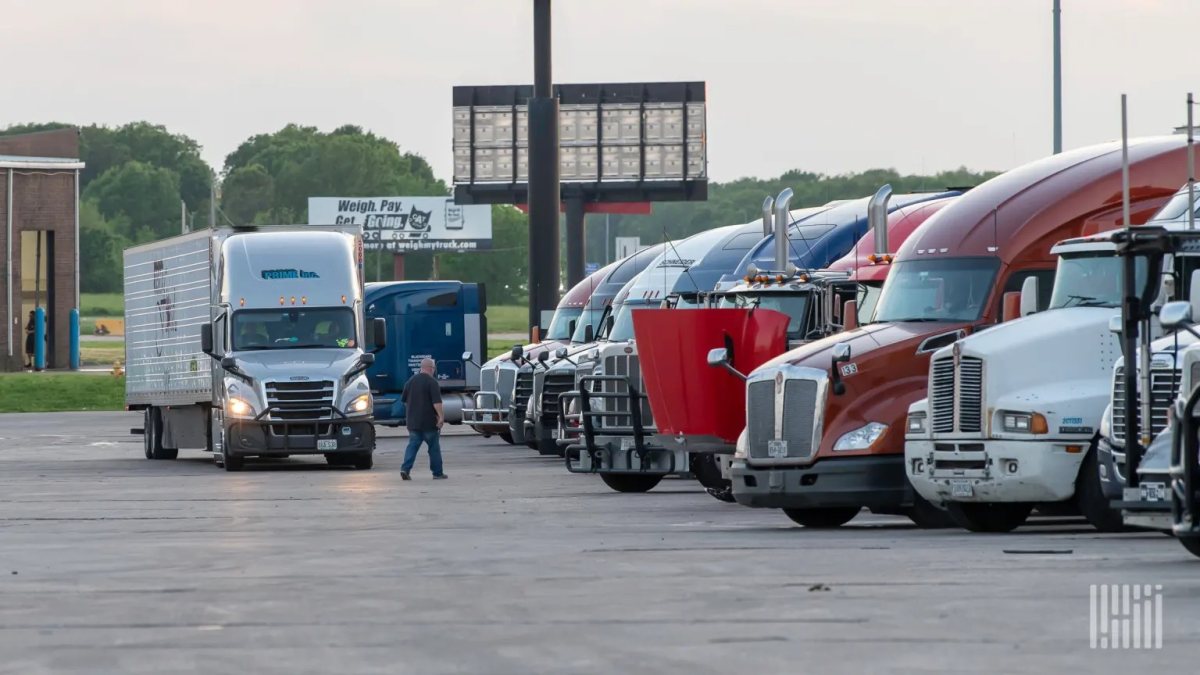
Transportation capacity has now contracted for 11 consecutive months, according to the October Logistics Managers Index released Nov. 3, with the Transportation Capacity Index reading of 38 — well below the 50-point expansion threshold and down sharply from 54.5 a year ago. The reading arrived the same morning as October’s ISM Manufacturing PMI, and both reports reinforce the same trend: demand is building while capacity continues to fall short.
The overall LMI came in at 70.7 in October, up from 70.2 in September and 13.3 points higher than the 57.4 recorded last October — the second-highest reading in four years. Transportation prices, the most dramatic mover in the index, surged from 61.7 last October to 88 this October. Respondents expect that figure to climb above 90 over the next 12 months, signaling no expectation of pricing relief.
“Transportation capacity is at 38. It’s continuing to sit in that contraction portion of the report at under 50 for the 11th straight month,” said Julie Van de Kamp. “A year ago it was at 54.5. All the way down to 38 this month.”
This story was originally published by FreightWaves. Read the full story at FreightWaves →
Conversation