
Sub-Saharan Africa: The Majors’ Next Wave of Growth
Sub-Saharan Africa (SSA) is set to play a defining role in the Majors’ next phase of growth. With capital discipline having constrained investment in recent years…
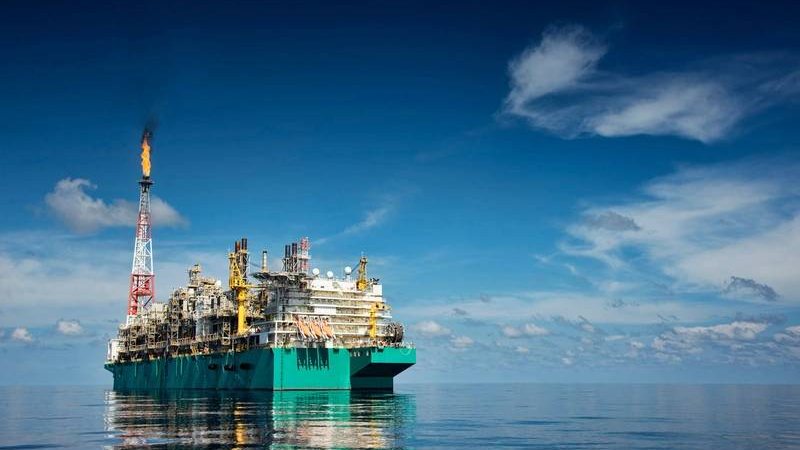
Sub-Saharan Africa (SSA) is set to play a defining role in the Majors’ next phase of growth. With capital discipline having constrained investment in recent years, base production across the peer group’s portfolios will decline before the end of the decade.
TotalEnergies has the strongest outlook, with Tilenga and Kingfisher in Uganda due onstream in 2026/27. Eni will add ~100,000 boe/d by 2029 from the recently sanctioned Coral Norte, Baleine Phase 3 and Azule-operated Greater PAJ projects. Despite sanctioning the Aseng gas monetisation project in April, Chevron faces the steepest decline of the peer group.
If the next wave of big-ticket projects take FID in the next 12 to 18 months however, these pre-FID projects can add up to 1.2 million boe/d at peak. Shell and ExxonMobil account for over half of pre-FID peak production.
ExxonMobil is expected to sanction Rovuma LNG in Mozambique later this year, which would be its first operated LNG project in the region. Large gas developments in Tanzania add meaningful volumes for Shell and Equinor, however, compared to neighbouring Mozambique, the country has struggled with regulatory commitment – a key risk that could have a major bearing on first gas.
This story was originally published by Offshore Engineer. Read the full story at Offshore Engineer →
Conversation