Truckload Pricing Power? Diesel Is Eating It Up
Truckload rates are up, but carrier profits still aren’t following. JB Hunt, Werner and Heartland earnings all point to the same freight market story: pricing power is back, but diesel, driver and insurance costs…
Truckload rates are up, but carrier profits still aren’t following. JB Hunt, Werner and Heartland earnings all point to the same freight market story: pricing power is back, but diesel, driver and insurance costs are eating the gains. In this update, we break down what the latest earnings say about truckload and intermodal, why road-to-rail conversion is accelerating, and how SONAR data backs it up. Key numbers include diesel up 72% year over year, contract rates up 18%, and intermodal showing a 30% cost savings benefit versus highway in today’s market.
Truckload carriers are posting double-digit revenue growth this earnings season, but a 72% year-over-year surge in diesel prices is consuming most of those gains before they reach the bottom line. The dynamic, playing out across results from J.B. Hunt, Werner, and Heartland Express, signals that contract rates — up 18% year over year — will need to keep climbing just for carriers to hold margin.
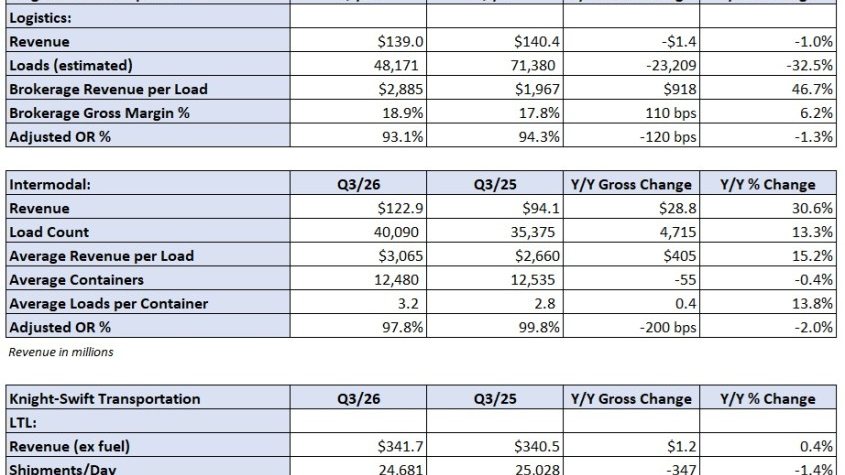
J.B. Hunt’s third-quarter results offer the starkest illustration. Operating revenue climbed 24%, driven by stronger pricing, an 8% increase in intermodal loads, and higher broker volumes. Yet net earnings rose only 1%, with driver-related expenses, fuel costs, and insurance claims absorbing nearly all of the revenue gain, said Julie Van de Kamp in a FreightWaves video update recorded Wednesday, October 21st.
This story was originally published by FreightWaves. Read the full story at FreightWaves →
Conversation