Floating Production Outlook: Pipeline Looks Huge, But Not All Projects Are Created Equal
Global floating hydrocarbons and electricity production and storage infrastructure (floating units) has a sizeable development pipeline through 2035, but the gap between identified projects and committed work is substantial. Intelatus Global Partners tracks 711…
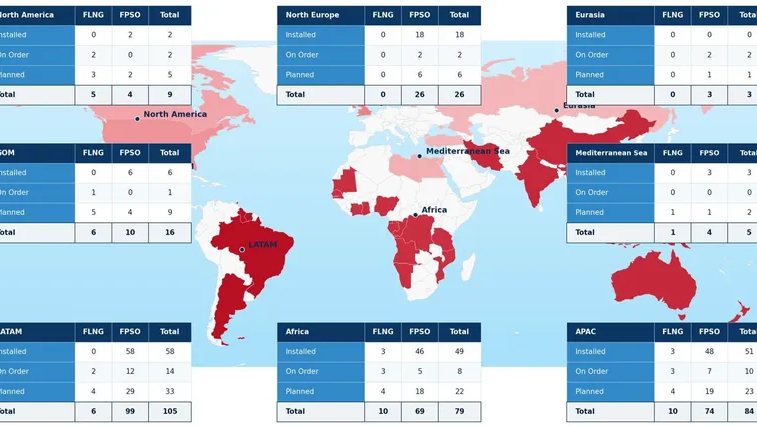
Global floating hydrocarbons and electricity production and storage infrastructure (floating units) has a sizeable development pipeline through 2035, but the gap between identified projects and committed work is substantial.
Intelatus Global Partners tracks 711 floating units worldwide, including 232 planned or on-order facilities with expected first-production dates in 2026–2035 .
The commercial implications extend beyond floating unit construction. A deepwater FPSO in LATAM, a SEMI in the Gulf of Mexico, and an FSRU at a coastal terminal involve different mooring systems, installation sequences, and vessel requirements. For mooring suppliers and offshore support vessel owners, project maturity, water depth, and regional charter conditions will determine how much of the identified pipeline becomes executable work.
Analysis covers 460 installed, 72 on order, 174 planned, and five available units. APAC leads the installed fleet with 137 units, followed by LATAM (93) and Africa (89). FPSOs account for 181 installed units, ahead of FSOs (74), FSRUs (48), and SEMIs (40) .
This story was originally published by MarineLink. Read the full story at MarineLink →
Conversation