The Lag Effect: Trucking Capacity Declines as Rates Recover
Truckload rates rose far faster than costs in 2026, yet carriers keep failing. SONAR data shows why, and what it means for 2027 contract bids.
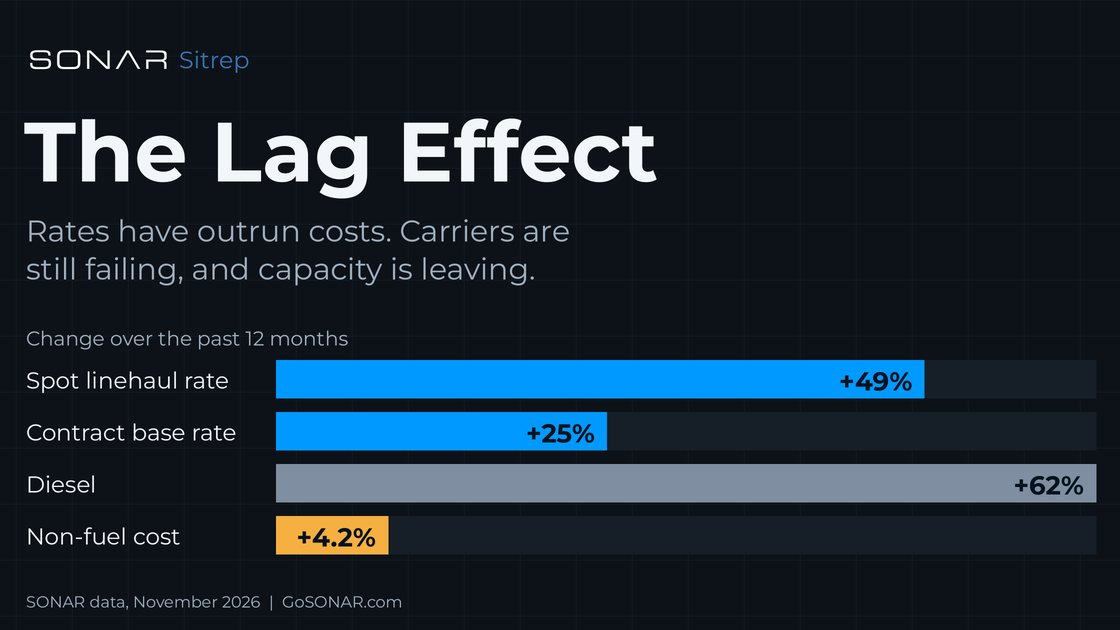
SONAR’s new Sitrep, The Lag Effect, shows rates rising far faster than costs, capacity leaving at a record pace, and contract rates with more room to run in 2027.
Truckload rates have finally outrun the cost of running a truck. SONAR’s spot linehaul index (NTIL) is up about 49% in a year and dry van contract base rates (VCRPM1) about 25%, while industry non-fuel operating costs rose 4.2%. Yet more than 1,000 logistics job cuts and 15 bankruptcy filings landed in just a few weeks this fall.
Both things are true at once, and the reason matters for every shipper heading into 2027 bids. SONAR’s new Sitrep, The Lag Effect, breaks down the data.
Yes. Spot linehaul (NTIL.USA) is $2.60 a mile, about $0.75 above ATRI’s 2025 industry non-fuel cost of $1.854. That reverses three straight years, from 2023 through 2025, in which spot linehaul ran below carriers’ non-fuel costs.
This story was originally published by FreightWaves. Read the full story at FreightWaves →
Conversation