Xeneta Air Outlook 2027: one shock, one recovery, and what comes next
When we published the Air Outlook 2026, we flagged geopolitical wild cards as a key risk. On 28 February, one arrived. Military strikes closed Gulf airspace and removed about 12% of global air cargo…
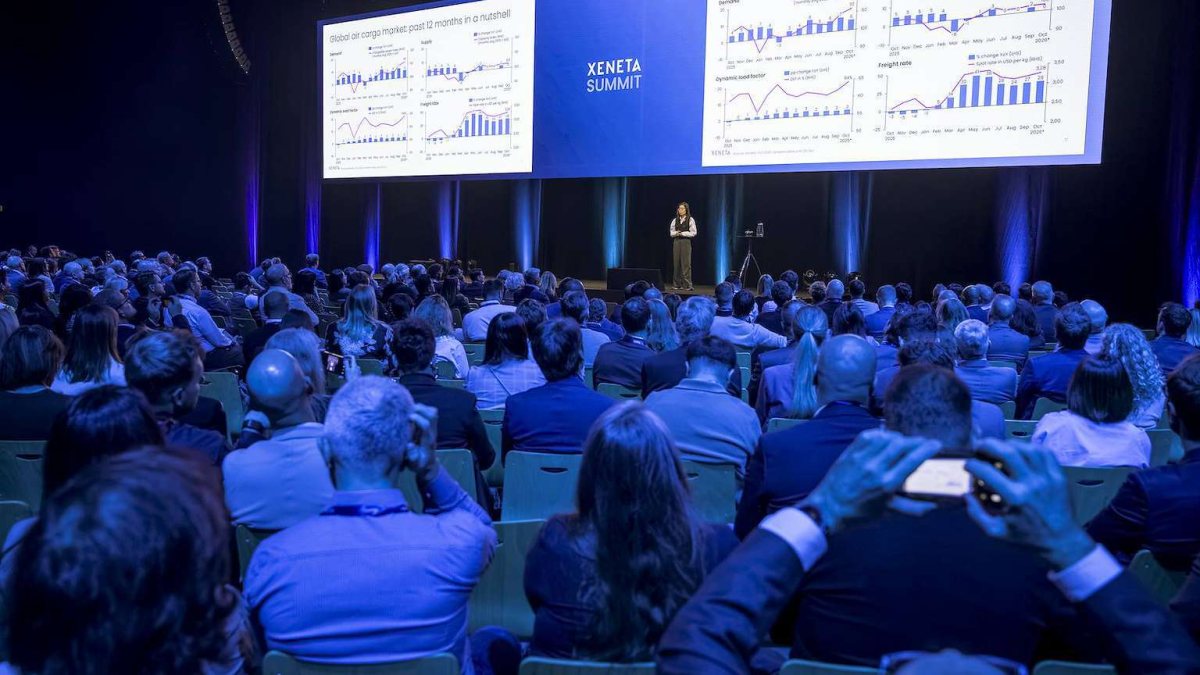
When we published the Air Outlook 2026, we flagged geopolitical wild cards as a key risk. On 28 February, one arrived. Military strikes closed Gulf airspace and removed about 12% of global air cargo capacity overnight.
What impressed us most was how quickly the industry responded. European and Asian carriers flew Asia–Europe direct, and the Gulf carriers rebuilt their networks through the spring. The conflict did not shrink the world's air cargo capacity; it slowed its growth. Global capacity is now 2% larger than a year ago, having grown at 6% before the strikes.
The recovery is not yet complete. Far from it. Eight months on, Gulf-origin capacity is 87% of last year, and the Middle East–Europe corridor sits at 75%.
Rates responded directly. Airline average rates into the Middle East were up 48% year on year in October, while most other corridors have given back their March spike.
This story was originally published by Xeneta Blog. Read the full story at Xeneta Blog →
Conversation