Diesel cracks stay high but seaborne supply points to easing
Middle distillate cracks remain elevated, with Northwest Europe diesel near $88/b and jet/kero near $85/b as of 6 November (Argus). Tight Atlantic Basin inventories have underpinned this strength, but seaborne flows point to a…
Middle distillate cracks remain elevated, with Northwest Europe diesel near $88/b and jet/kero near $85/b as of 6 November (Argus). Tight Atlantic Basin inventories have underpinned this strength, but seaborne flows point to a loosening ahead, although the pace will depend on several factors.
Russia is the largest swing factor Repeated attacks on Russian refineries have curbed product output and led to export restrictions. Diesel/gasoil exports from its Baltic and Black Sea ports fell to a dataset low of 150kbd in August, from 755kbd in August 2025. However, exports have picked up since mid-October, surpassing 350kbd as of 6 November (28-day MA). In October, refinery attacks fell to their lowest in six months (based on official reports and Telegram channels). A return to last year’s levels would nearly triple current volumes, although that depends on the intensity of any further attacks and the speed of repairs.
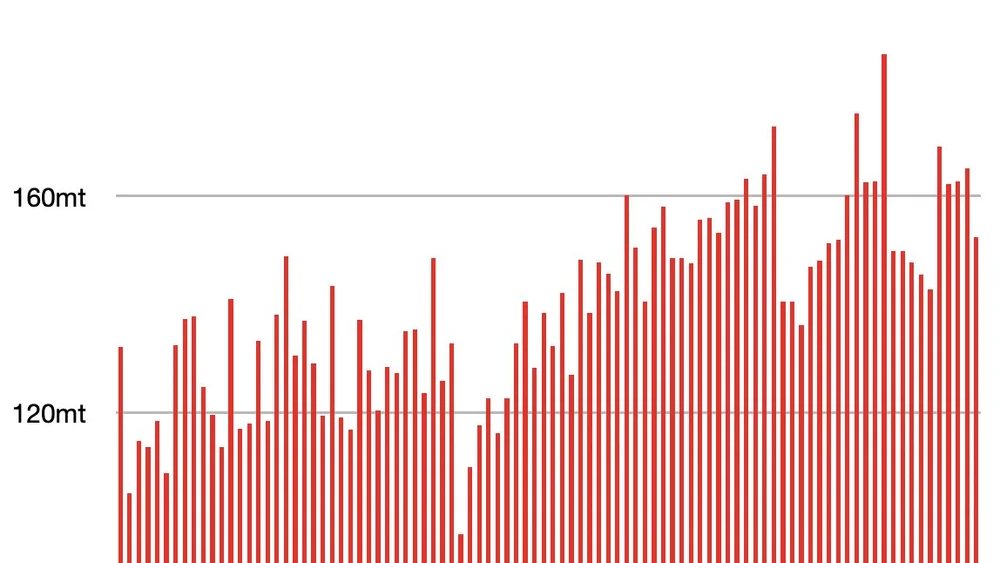
Exports outside Russia are at a record high Global seaborne middle distillate exports excluding Russia reached a record high in the Vortexa dataset of 10.2mbd as of 6 November (28-day MA), 20% above the 2016-25 seasonal average.
Chart: Global seaborne middle distillate exports (excl. from Russia) (bd, 28-day moving average)
This story was originally published by Hellenic Shipping News. Read the full story at Hellenic Shipping News →
Conversation