Midterms strip out the war premium, but the next two months make shorts a risky bet
Crude futures have just posted their sharpest sell-off since 2020. Brent fell 16.6% between the 30 October peak and 4 November. On that day the January contract settled at $94.62/bbl after an $8.98/bbl drop.…
Crude futures have just posted their sharpest sell-off since 2020. Brent fell 16.6% between the 30 October peak and 4 November. On that day the January contract settled at $94.62/bbl after an $8.98/bbl drop. The trigger was the Democrats’ sweep of both chambers of Congress, which the market read as raising pressure on Washington to wind down the war with Iran.
Trend-following CTAs amplified the move, selling around 126 mbbl across crude and products since 30 October, including 52 mbbls on 4 November alone. Brent has since rebounded to around $97/bbl amid fresh tanker incidents in the Hormuz Strait, and prompt spreads have firmed, but it remains on course for a weekly loss of roughly 12%.
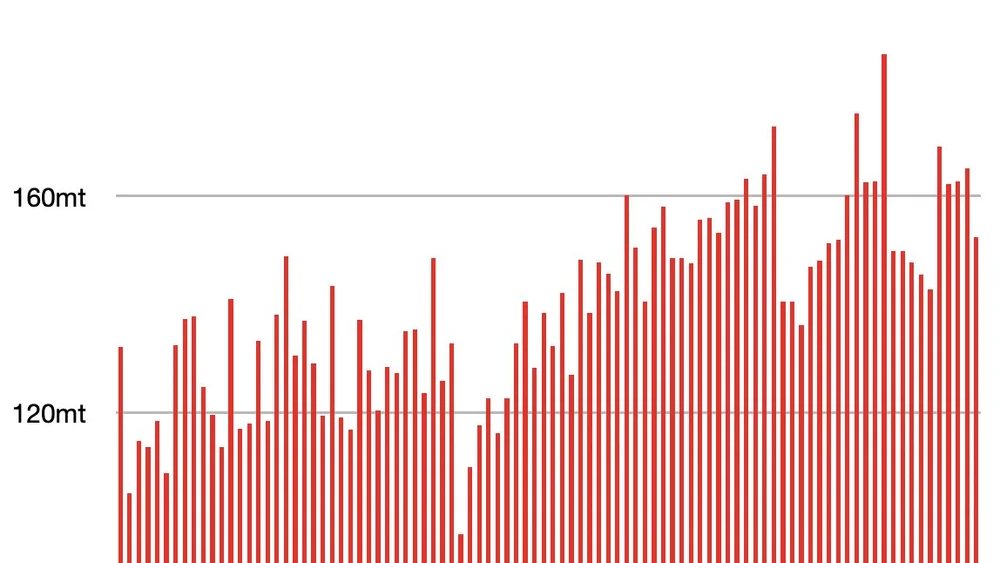
The sell-off confirms what we flagged in The Crude View and this month’s House View: the war’s price had moved out of the barrel and onto paper, as futures had always been where geopolitical risk premium sits. October was the heaviest month of the war, with 35 vessel attacks. Even so, crude flows exiting the region remained high, averaging 16.6 mbd in October (excluding Iranian oil), down 500 kbd against 17.1 mbd September and also against pre-war flows.
This story was originally published by Hellenic Shipping News. Read the full story at Hellenic Shipping News →
Conversation